
Buying cars in yo 20's
-
I_love_cars: not everyone has the same mindset. While we seem to view being "successful" as having enough time and money to do whatever we please (maybe I'm wrong), others don't feel the same way. Some people like a stable routine in a field that is much harder, or impossible to do as an entrepreneur.
There will always be someone with more money than you, more time than you, and who is even better at what you do. You need to be happy with yourself at the end of the day, whatever that means. I'm only 23, so maybe I don't know what I'm talking about. Oh well.
EDIT: Proud'a'yu
Well, to be clear, time and money to do as we please is more of just a result of the efforts, it isn't the driving goal behind it. The goal is still freedom to do things on your own terms. That may not mean having a ton of money. I know guys who make 50k a year on their own but the do it not having to answer to some stupid corporation. They're pretty happy.
I personally am after security for my family and friends. I've had too many people in my life get fucked over by stock markets and/or piss poor planning. These are people I care about, I don't blame them because most people are just conditioned at an early age to behave a certain way and it has consequences. I've been at this investment firm for the past 4 years. We have the highest per capita profit in the industry, bar none. But that comes at the cost of making other people lose. The stock market is never something that I have really believed in because by its very definition, the only way to win is for someone else to lose. I don't like that model.
I prefer rental properties because I control it, I control where it is, I control how well it's kept and how good my tenants are. I am able to provide affordable rent rates lower than most in the market right now because I'm not greedy and would rather see people have some options. Everyone needs a place to live, and I like being able to do what I can to help people with that.
The goal is to ensure that no matter what happens, my family and friends are taken care of. Honestly I will always be into software and "work" that way in some capacity because I love that stuff. It's a passion, but I never ever want to say past the age of 40 that I'm beholden to that. To me, land is a strong bet. Markets were created by man and have gaping holes that screw people over. Land has stayed consistent for thousands upon thousands of years. In Rome, you needed land to vote. Land has always been a bartering tool. People always need a place to live. There is really no way that housing can fail you as long as you are insured for catastrophe and also manage your cash flow effectively.
I'm not in the ball park of ever getting millions of dollars this way. But I will damn sure not have to subject my family to me being unemployed and wondering WTF to do when I'm 55 or 60. That's my goal.
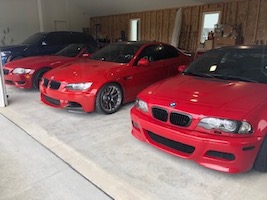
2011 E92 M3 6MT ZCP - ESS 625 supercharged
2007 Z4MR
2003 E39 M5
2002 E46 M3
2021 X5 40i -
This thread 10/10 would read again.
It's pretty interesting stuff
-
A whole lot to cover in one post! I believe the most important point you made, is do something that makes you happy.
My back up plan, just so happens to be the job I'm currently at. Rowley Tool Corp. My great grandfather started this place in 1945, and then my grandpa, and currently my second cousin's own it.
The reason I chose this path, is for 1, it make me HAPPY! I absolutely love building stuff every day, I love my hours, and I love working 40 hours a week. I know exactly what time I work next year feb 2nd(random date) but I have no clue what I will be doing. I know where, I know when, but its always different(its like the job was made for me!).
Another reason I choose it, is because I don't have to put my goals on pause(Starting my own business, of course), yet I will end up with a back up plan if my businesses ever goes down hill. I will be able to get a job anywhere with a Tool and Die journeyman's card. No, this is definitely not the end goal.
lastly, my boss just so happens to be 65. His brother(the other boss) is roughly the same age. I would have to say, that this place is one fantastic place to work if you are doing tool and die, I couldn't imagine a better shop work environment. I believe I will have what it takes to steer this place in the right direction when the time comes, and that just might be my destiny.
But if not, If the time comes when the shop will be shut down, My house will be paid off(But more importantly my shop will be done) I will have a back up business hopefully in full swing, and I will have a backup career if those business's go down. I'm currently doing what I can to invest in my own business.
Would you believe thats the best place to put my money during this age?
I almost forgot we were talking about buying a car.

sk8 or die
-
But I gotta wonder why you think buying a house was a bad idea.
I have a 5 year contract for my apprentice, so I knew I needed to stay local for at least 5 years, and I needed a place to live no matter what, and more importantly I needed a place TO WORK ON MY CARS.
The house is tiny, it will be paid off before the 5 years are over, and the biggest reason I bought it is that it comes with a 24x36 shop. Which happens to be larger than the house haha.
And its cheaper than paying rent if I need it to be! Not to mention paying rent is like pissing money out the window.
sk8 or die
-
It's fine if you'll live there for 30 years. As far as an investment goes, don't houses "appreciate" at like .8% a year or something...? Not only that houses don't appreciate like they use to. Sure, you build equity; and your mortgage may be cheaper than renting a similar dwelling. But you have taxes/repair/etc. how long does it take for your payment to actually affect the principal rather than just paying off the interest? How about home owners insurance? It's like renting. From a bank.
-
The reason some people think owning a house is bad, is because of the money you are spending on the house (mostly in interest) that could be going to other investments. A huge portion of my income goes to the house, interest, mortgage, upkeep, taxes, etc. I could be using that money to build wealth.....much more than my house will be worth when it is all free and clear (yet I still pay taxes and upkeep).
The argument, is that I want a nice house, it makes me happy, it's great for my family, and I get to have a place to keep all my fun stuff at.
-
Different strokes for different folks. It's nice being able to leave after a year if I want with no strings. But then again I don't get the benefits of doing whatever the hell I want to it.
If I had a family my views would be different for sure, as Robert mentioned above
-
Different strokes for different folks. It's nice being able to leave after a year if I want with no strings. But then again I don't get the benefits of doing whatever the hell I want to it. If I had a family my views would be different for sure, as Robert mentioned above
You sound like you're single.
I have 1000$ a year on taxes, 600$ a year on insurance(IT actually cut my car insurance in half, which saved me much more than 600$ a year) and about 1300$ a year on interest, but thats only going to be for the first 5 year( of course this number gets lower as I pay in).
What I'm getting at. I can't see renting a place being much cheaper. And since my father and uncle are contractors, I'm not worried about fixing it. Very minimal fixes will be needed. As you can see, taxes and interest aren't much at all.
at worst, if no one buys it for near what I paid, I can rent it out. Or not? Oh well. Its only a 32k house! always need equity.
sk8 or die
-
I'm Not single.
I just try to be smart with my money before committing 30years of my life to something I most likely won't get my money out of. Equity can be made elsewhere if need be.
-
This is a big reason why I chose to purchase a duplex instead of a single family home. I rent the upper to people I know and I live in the lower. Half the mortgage is paid for me, all major renovations and appliances were done/replaced by previous owner, I get to do whatever the crap I want (just like owning a single family home as you guys previously mentioned) and at the end of the day, could just as easily rent the whole thing out and put money in my pocket.
-
I'm Not single.
I just try to be smart with my money before committing 30years of my life to something I most likely won't get my money out of. Equity can be made elsewhere if need be.
Congrats! When's the wedding?
-
Congrats! When's the wedding?
Whenever earls car is done
-
The way that a mortgage amortizes makes homes in your early 20's a bad investment vehicle. The first 10 years of a 30 yr mortgage are going to be almost entirely interest. Your only equity at that point is in upgrades or market appreciation. In raw dollars, a house usually is worth 80%-100% more than when you bought it if you pay it off at term of 30 years. However, you have also paid nearly double your original purchase price in interest, plus repairs, potentially PMI, potentially HOA, and HOI. So in reality you aren't really coming out ahead. All you're doing is at best breaking even unless you're in a housing bubble, but you can't plan for that or bank on it. That's just stupid. If you turn around and say "well I am paying extra on principal every month", ok great, except for the fact that the money is doing utterly nothing for you right now because you won't see any of that money come back until you sell the house (maybe) X number of years down the road. You aren't doing yourself any favors. Time/value of money says that's a bad idea when you're starting out. Especially on a secured piece of debt like a house. If you meet LTV ratios you can potentially take a line of credit out, but only if you put 20% down and then after that over the course of let's say 3 years if you are paying down principal, you are freeing up what? A few thousand bucks? Big deal that won't be you much at all if you are taking out a HELOC.
also, most of the money you sink into a house is money you won't ever see back. Furnace, A/C, water heater, roof, windows, landscaping, driveway/walkway/stoop repair, or foundation (god help you at that point), are tens of thousands of dollars that contribute absolutely nothing to increasing the value of a home in the real marketplace. The majority of buyers don't give a shit about anything other than floor plans + whatever the current trend is in kitchens and bathrooms. Those are your biggest money makers.
If you get a house for let's say 32k like Rowley, there's really no harm in that because you can realistically pay it off very quickly. But you aren't going to get much house for 32k and certainly not as much resale value if it's that small (as noted smaller than 24x36) in the starter home market. But you also can't say it's cheaper than renting because right now in real terms it may be, however, any time you own a house you are taking a risk on what will break and it could be something significant. If you start having water problems in a basement before 5 years is up and you want to sell it? Have fun. You're either fixing it or sitting on it for a long time, or you're selling it for next to nothing because buyers will beat your ass up on the price.
But if you're renting? You have 0 liability for stuff like that. All you need to do is not be a shitfuck and don't destroy the place you live at.
It's about risk mitigation - if you are trying to achieve something that requires X number of dollars like start a particular business that has particular overhead costs or whatever, your best bet is to mitigate your risk of out-of-pocket expenses as much as possible.
I started out with duplex with my wife and daughter, we lived there for 2 years. Then I bought a rehabber, lived in my in-laws' basement for 6 months while I went to my day job and then worked 6 days a week till 11 p.m. every night redoing 4 bathrooms, 2 kitchens, 1500 sq ft of hardwood floors, the list goes on. Then I moved in there for 2 years and it cost me 400 bucks a month to live there. I was able to sell that place for a significant profit. That place paid for the down payment on my business partner's single family home for himself, it paid for my absurd 15k engine build on my Acura TL, and eventually helped me get into the house i'm in now. Meanwhile I was looking for other duplexes. I found a place near Mt. Mary college that my partner and I bought. Looking hard at cost per unit - it was about 60k per unit for that duplex, and market rent is 750-800/mo per unit. 1 unit rented literally pays for everything at that point. The rest is just profit that all gets either repair escrow or goes to paying down the principal.
all of these things have something in common which is mitigating cost by being patient for proper deals and understanding neighborhoods, cap rates, likely scenarios, etc. , and mitigating risk by never taking anything for ourselves. In 8 years all my cash flow from property has gone into principal or escrow for repairs.
I pay my mortgage on my house that I live in now out of pocket because I have a wife and 2 young kids and we lived light for years and I shuffled them around and moved them from one place to the next 6 or 7 times probably in the past 7 years. Eventually there is an intangible benefit when you have a family to just stabilizing some things for them first, and then re-focusing on investments. But I still can't help but see myself as throwing money away at interest and risk of repairs here which will eat into my investing power. To me, I can't see it any other way - I hate the fact that I pay for my house out of my pocket and can't use other people's money to do that. i.e. profit from investments. But I made the decision to have a family and not sacrifice everything for the sake of just money. I acknowledge this and I never would criticize someone for going the route I did but I also will advise any early 20-something to be serious about what they want out of life and figure out how to get there, understand the roadblocks/events that can happen to slow that down, and understand what you are willing to live with and be happy with.
For me, it all comes back to the OPM formula. Renting to people to have them pay your taxes, mortgages, interest, and repairs is a form of OPM , and the money to get the property they rent in the first place is from a bank of course which is OPM but again with cash flow from tenants, I'm insulated. So when I say buying a house in your 20's that you aren't using to either A) flip short term and can make actual money on, or
 rent out , is a bad idea, that's what I'm getting at. If you have 0 aspirations to do more with your life, fine do whatever you want and buy your house. If you have some amount of aspirations but obligations like family get in the way, then balance it at least and buy a cheaper starter home in a stable area. Exit strategy is everything. I never buy anything without an exit strategy. It either needs to be cheap enough under market value that I can sell it for what I paid for it even with my back against a wall or with minimal loss, or cash flow like a mofo so nobody can beat me up bad enough on price because I can always justify the cap rate, or it has to be in a neighborhood that has 1 in a million chance of going downhill (like the neighborhood I currently live in). Thirdly, if you have nothing but aspirations and 0 ties to anyone like kids or a wife, then don't a screwup - mitigate as much as you can.
Why? Time/value of money says so, that's why. Your time is cheap in your 20's, so every dollar you can push for yourself to get closer to your goals whatever they may be is amplified that much more because you have tons of time to fail fast and recover with your ideas and aspirations.
2011 E92 M3 6MT ZCP - ESS 625 supercharged
2007 Z4MR
2003 E39 M5
2002 E46 M3
2021 X5 40i -
I'm trying to "not be a shitfuck" currently.
That line cracked me up xD
-
Man all this stuff is making me seriously rethink all the choices I've made in my life thus far haha. I thought for once I made a good decision to buy a house. I asked many very successful people for help and they all said it was a great idea.
If the real goal was to buy one big ass piece of property and build my dream house/shop/raise a family, am I doing it right? Should I not continue to throw lots of money towards the principle?
Secondly, the back up plan if I can't sell it, is to rent it. The house was actually a rental for many many years, and they just put it for sale becauSe the landlords were very old.
I'm pretty clueless.
But I grew up in a 5000 sqft house with 3 master bedrooms, 10 other bed rooms, 6 bathrooms, etc, and what I know, is that all I wanted was a REALLY small house, and a shop. And I definitely got that haha. I couldn't imagine achieving that goal for any cheaper! And no matter what I can't lose that much can I?
Sent from my iPhone using Tapatalk
sk8 or die
-
I've gotten a lot of advice from a lot of independently wealthy people as well and the advice varies wildly. You don't take it all as gospel - you have to have some intelligence about you and self-awareness of the world you currently live in. What someone did 15-20 years ago is not necessarily going to work today. And similarly what works for 1 person won't work for another because some people's dispositions/mentalities and work ethics allow them to be successful in different ways.
For example - I know people who recommend buying multi-families in the ghetto of milwaukee because you can get properties for dirt cheap, but rent is still pretty similar whether you are on the North side in the ghetto or in a 800 sq ft rental in Tosa. Your cost per unit is super cheap, and tons of your tenants are on Section 8 government assistance which means the govt directly deposits rent into your bank every month, but you have to hire a manager to deal with other bill collections and you have to deal with shitty people who will destroy your property. You can make millions that way. But it's not for me. I'm not that type of investor.
I prefer to get places where I could see myself living, in predominately single-family home neighborhoods where there aren't a ton of other rentals which will keep property value higher, and attract better tenants. It's less immediate reward but also less risk.
And when I talk about being self-aware about the world you live in - really we're talking about ways of investing change over time. Chew on the following for a minute:
What most people you're talking to don't understand is that we are not in a world anymore where housing is that much of a springboard. When those people were younger, even 10 years ago, it was a different story. There was a LOT more opportunity to exponentially grow. I know people who built huge homes and used the equity in them before they were even done being built to buy multi-family rental buildings. Banks won't let you do that anymore. That was happening when you could leverage a property for HELOCs at 100% LTV as opposed to 80/20, and when the market tanked it went down to like 70/30 - so literally you had to own 30% before you could even have a discussion about taking out a heloc to buy other property with.
The key word here is "exponential". The people who are extremely wealthy/successful were in opportune times and seized that opportunity for exponential growth. That is no longer the world we live in - or rather, the opportunities are much much harder to come by. You have to be smarter, especially when you are starting out. Many people fail miserably because they overpay for their first duplex or 4 family, don't manage the cash flow right, and in 2015 there is very little in the way of good exit strategy at that point because the market isn't improving your property value. I looked at about 100 properties before I bought my first place in 2008. Took me about a year and a half, started looking in early 2007.
I have had to put down at least 20% on residential, in some cases 25%, and as of a couple years ago, there are new Fannie/Freddie guidelines that explicitly say Fannie/Freddie won't buy mortgages from banks if the borrower has more than 4 properties. This makes it extremely hard for young people like us starting up to get in the game and exponentially grow, because nearly every bank you will ever talk to is going to want to sell your loan to F/F, regardless of if you got a conventional loan or an FHA loan. So after you've bought a few properties with 20%+ down payment, which basically is forcing 99% of all 20-somethings to spend every nickel and dime they have just to get a small foot in the door with such large down payments (for historical reasons leading up to the housing bubble burst), now if you want to go further you need to either have really wealthy networks of people who will bankroll you, or you need to be in tight with a small-business bank that will hold on to your loan. Neither of those entities are easy to get ahold of. Many small business banks require you to have deposits sometimes in excess of 1 million dollars before they will even touch you.
Homes aren't increasing in value much right now, and certainly not at a rate where you can leverage them for anything. If you want to rent the home out, that's all good and well, but do not ever let anyone convince you that in the year 2015, buying a home in your early 20's is going to help that much. It won't. By the time you see any significant increase in value that you can actually use, you'll be over 30 years old.
Again, time/value of money is the key to remember. What are you trying to accomplish and in what timeframe, and understand that a house right now is not going to propel you. You'll get more value out of a rental that cash flows at a really good cap rate so that it pays for itself/repairs, and also helps build cash for more property. At that point you can start thinking about finding partners. A lot of people, even successful people who are older in the commercial property space - they all have partnerships. None of those people got to that particular level on their own. So if you have something making cash for you that you can sock away, and can find likeminded people to invest with, you can go a hell of a lot farther.
Do you want to own 5% of something or 100% of nothing? The first property I bought I covered 25% and my partner covered 75%. I don't care because I needed to get going and I'd rather have that 25% in the long-run. 50% would be nice but the alternative would be......0%.
2011 E92 M3 6MT ZCP - ESS 625 supercharged
2007 Z4MR
2003 E39 M5
2002 E46 M3
2021 X5 40i -
I just want to say that there is a lot of great info in this thread. I might not be directly responding to it, but I'm definitely reading it.
Would love to hear other opinions as well. I was going to save to put $15k down on a $100k house, but might be better off renting. I'm not sure. The apartments I'd really like are $800/mo. I'm sure a mortgage and rent would be similar after all utilities and other expenses, I just wouldn't have any risk or duties in an apartment.
-
I'd like to build a 2 1500sq/ft unit shop condo for $96k and rent out the one unit to pay the mortgage. Saving for 15-20% down payment will take a while vs just renting a unit right now though. That's my long goal that I hope to achieve within a couple years. Buying a duplex home has always been one of my plans too.
-
I really need to start thinking about this. I'm already not being so smart with my money since my car has taken roughly 20K...
Think of the scene point ROI though
Hello! It looks like you're interested in this conversation, but you don't have an account yet.
Getting fed up of having to scroll through the same posts each visit? When you register for an account, you'll always come back to exactly where you were before, and choose to be notified of new replies (either via email, or push notification). You'll also be able to save bookmarks and upvote posts to show your appreciation to other community members.
With your input, this post could be even better 💗
Register Login