
Buying cars in yo 20's
-
I've gotten a lot of advice from a lot of independently wealthy people as well and the advice varies wildly. You don't take it all as gospel - you have to have some intelligence about you and self-awareness of the world you currently live in. What someone did 15-20 years ago is not necessarily going to work today. And similarly what works for 1 person won't work for another because some people's dispositions/mentalities and work ethics allow them to be successful in different ways.
For example - I know people who recommend buying multi-families in the ghetto of milwaukee because you can get properties for dirt cheap, but rent is still pretty similar whether you are on the North side in the ghetto or in a 800 sq ft rental in Tosa. Your cost per unit is super cheap, and tons of your tenants are on Section 8 government assistance which means the govt directly deposits rent into your bank every month, but you have to hire a manager to deal with other bill collections and you have to deal with shitty people who will destroy your property. You can make millions that way. But it's not for me. I'm not that type of investor.
I prefer to get places where I could see myself living, in predominately single-family home neighborhoods where there aren't a ton of other rentals which will keep property value higher, and attract better tenants. It's less immediate reward but also less risk.
And when I talk about being self-aware about the world you live in - really we're talking about ways of investing change over time. Chew on the following for a minute:
What most people you're talking to don't understand is that we are not in a world anymore where housing is that much of a springboard. When those people were younger, even 10 years ago, it was a different story. There was a LOT more opportunity to exponentially grow. I know people who built huge homes and used the equity in them before they were even done being built to buy multi-family rental buildings. Banks won't let you do that anymore. That was happening when you could leverage a property for HELOCs at 100% LTV as opposed to 80/20, and when the market tanked it went down to like 70/30 - so literally you had to own 30% before you could even have a discussion about taking out a heloc to buy other property with.
The key word here is "exponential". The people who are extremely wealthy/successful were in opportune times and seized that opportunity for exponential growth. That is no longer the world we live in - or rather, the opportunities are much much harder to come by. You have to be smarter, especially when you are starting out. Many people fail miserably because they overpay for their first duplex or 4 family, don't manage the cash flow right, and in 2015 there is very little in the way of good exit strategy at that point because the market isn't improving your property value. I looked at about 100 properties before I bought my first place in 2008. Took me about a year and a half, started looking in early 2007.
I have had to put down at least 20% on residential, in some cases 25%, and as of a couple years ago, there are new Fannie/Freddie guidelines that explicitly say Fannie/Freddie won't buy mortgages from banks if the borrower has more than 4 properties. This makes it extremely hard for young people like us starting up to get in the game and exponentially grow, because nearly every bank you will ever talk to is going to want to sell your loan to F/F, regardless of if you got a conventional loan or an FHA loan. So after you've bought a few properties with 20%+ down payment, which basically is forcing 99% of all 20-somethings to spend every nickel and dime they have just to get a small foot in the door with such large down payments (for historical reasons leading up to the housing bubble burst), now if you want to go further you need to either have really wealthy networks of people who will bankroll you, or you need to be in tight with a small-business bank that will hold on to your loan. Neither of those entities are easy to get ahold of. Many small business banks require you to have deposits sometimes in excess of 1 million dollars before they will even touch you.
Homes aren't increasing in value much right now, and certainly not at a rate where you can leverage them for anything. If you want to rent the home out, that's all good and well, but do not ever let anyone convince you that in the year 2015, buying a home in your early 20's is going to help that much. It won't. By the time you see any significant increase in value that you can actually use, you'll be over 30 years old.
Again, time/value of money is the key to remember. What are you trying to accomplish and in what timeframe, and understand that a house right now is not going to propel you. You'll get more value out of a rental that cash flows at a really good cap rate so that it pays for itself/repairs, and also helps build cash for more property. At that point you can start thinking about finding partners. A lot of people, even successful people who are older in the commercial property space - they all have partnerships. None of those people got to that particular level on their own. So if you have something making cash for you that you can sock away, and can find likeminded people to invest with, you can go a hell of a lot farther.
Do you want to own 5% of something or 100% of nothing? The first property I bought I covered 25% and my partner covered 75%. I don't care because I needed to get going and I'd rather have that 25% in the long-run. 50% would be nice but the alternative would be......0%.
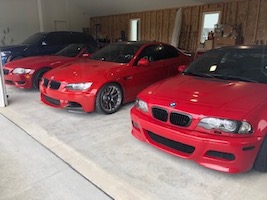
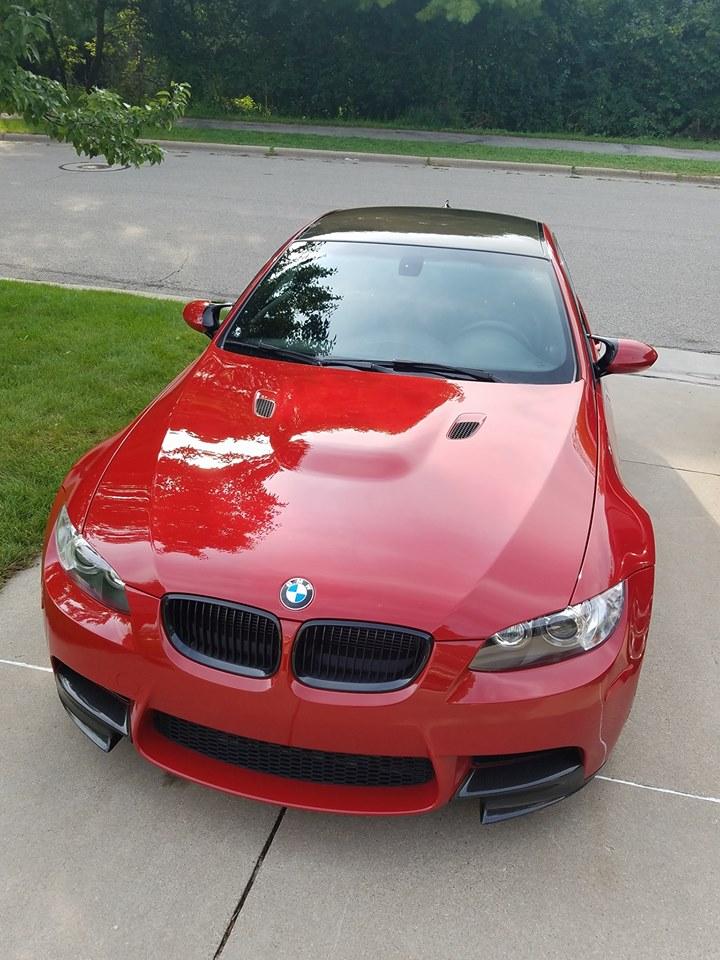
2011 E92 M3 6MT ZCP - ESS 625 supercharged
2007 Z4MR
2003 E39 M5
2002 E46 M3
2021 X5 40i -
I just want to say that there is a lot of great info in this thread. I might not be directly responding to it, but I'm definitely reading it.
Would love to hear other opinions as well. I was going to save to put $15k down on a $100k house, but might be better off renting. I'm not sure. The apartments I'd really like are $800/mo. I'm sure a mortgage and rent would be similar after all utilities and other expenses, I just wouldn't have any risk or duties in an apartment.
-
I'd like to build a 2 1500sq/ft unit shop condo for $96k and rent out the one unit to pay the mortgage. Saving for 15-20% down payment will take a while vs just renting a unit right now though. That's my long goal that I hope to achieve within a couple years. Buying a duplex home has always been one of my plans too.
-
I really need to start thinking about this. I'm already not being so smart with my money since my car has taken roughly 20K...
Think of the scene point ROI though
-
going in with less than 20% is common, normal, and doable if you are first-time buyer and are owner occupying the building. If it's an investment property (no owner occ), then you will struggle to get a bank to finance you at less than 20%.
I've always done at least 20%, however, PMI is based on 5% increments, so you pay more at 10% down than you do at 15%. You can balance the PMI with rent you collect on a duplex that you owner occupy and still mitigate cost well, and with at least a 10% down payment you should be able to sell it if you had to without totally losing your ass (unless it needs major repairs).
15k on a 100k house isn't awful because it is accurate to say that your month to month costs will be similar. If you are willing to do a little bit of work, though i.e. learn to be handy (the right way please - most handyman jobs i've seen at properties over the years are totally wrong/unsafe/not to code), screen tenants and whatnot - then I would never look at a 100k house with 15k down. I'd try to find a duplex to live in - I have looked at a lot of properties in the Oshkosh area over the past couple years - I know property managers in that area who would take 7-8% gross rent but the buildings cost 60-75k and you can still get around 1500/mo gross rent for the building at that point and make a killing.
Some people just flat out want to live in a house and for that, 100k home in your 20's with 15k down isn't bad because you are not stretching yourself out too far. But for what it's worth, if you want a slightly better position for yourself, doing the diligence to find a solid duplex for cheap is smart.
I would never, ever build a house. Incredible waste of money. You're paying at minimum 25% more than what you could get an existing home for in real terms of dollars per sq. ft and features.
I would only build a shop if I was running my business out of it and living out of it. There are plenty of properties available for purchase that are dual-zoned for commercial and residential that will cost you a lot less money overall. There was a sweet foreclosure a few years ago I was looking at in Tosa on North ave. by the sendik's - it was a duplex with 2 attached garage slots for shop work and those garages had an office attached to them. We got beat out by investors who would walk in and pay cash - we actually had a higher offer but the bank will always take a cash offer for a few thousand less because it's a cleaner/safer deal. Guaranteed the bank gets their money then so they always lean towards that when it comes to foreclosures.
2011 E92 M3 6MT ZCP - ESS 625 supercharged
2007 Z4MR
2003 E39 M5
2002 E46 M3
2021 X5 40i -
In the mean time, before I buy a large piece of land, where i will build my house(I'm sorry, no one builds a house like I want my house to be like, and my father is going to build it with me. Always been a dream of mine, and i will do it), but that won't be for a while, and I want to get a good start on my business. But this requires me to either add on to my current shop, which I'm afraid I won't get any return on my investment when I go to sell the place(who buys a 750sqft house with a huge shop???).
would you simply find a shop to rent, find a shop to buy, or expand?

sk8 or die
-
Interesting Rent vs. Buy Calculator from the New York Times recently.
http://www.nytimes.com/interactive/2014/upshot/buy-rent-calculator.html?_r=0&abt=0002&abg=1
-
I really need to start thinking about this. I'm already not being so smart with my money since my car has taken roughly 20K...
$20k and no turbo....sad day
-
Interesting Rent vs. Buy Calculator from the New York Times recently.
http://www.nytimes.com/interactive/2014/upshot/buy-rent-calculator.html?_r=0&abt=0002&abg=1
Just filled this out lol.
Supposedly I made the right move. Renting a place for around 250$ a month would be the better move, but no way in hell could I rent a place for that.
I love my tiny house.
Sent from my iPhone using Tapatalk
sk8 or die
-
Interesting Rent vs. Buy Calculator from the New York Times recently.
http://www.nytimes.com/interactive/2014/upshot/buy-rent-calculator.html?_r=0&abt=0002&abg=1
visian, I'm not saying this applies to you, but anyone who takes this calculator seriously is an idiot.
This is the housing equivalent of taking life/relationship advice from EliteDaily.com
There are so many holes in this. The numbers are incomplete, the numbers that are present are sourced from national data that is averaged, does not factor in cost of living differences or the fact that home price growth varies wildly right now and the majority of areas are not seeing growth. Some 70% of new construction in this country is currently rental buildings, NOT single family homes. People talk about the residential new construction market coming back and what's never represented is what % of the new construction is rental buildings vs. single family homes. I had an article last year that referenced this with all the data that I wish I had bookmarked right now.
This calculator also does not factor a person's age/demographics i.e. how much money they earn vs. how young they are and as such how much they stand to increase over 10 years time and what that means for what they could or could not buy as investment drivers, and because it doesn't include ANY data on cost of living and how wildly that differs based on city, it's impossible to account for the fact that a younger person will struggle a LOT more with maintaining a house and living there compared to renting because of ever-increasing utility costs that, commonly in rentals heat/water are covered by the landlords, and how much even small repairs on a house cut into a young person's limited cash flow/income.
This is so misleading it makes my head spin. My god. There is no consideration for qualitative analysis here either - not that there can be because it's intangible and varies from person to person. But that's exactly why this cannot be taken seriously. If I had followed the output recommendation of this calculator without considering who I am and what my propensity is, I wouldn't even have half the net worth that I currently have at 32. And I'd have set myself back a decade in real terms as far as where my leverage and investing power would be.
Holy fuck. I'm not surprised though because after all it is the NY Times.
2011 E92 M3 6MT ZCP - ESS 625 supercharged
2007 Z4MR
2003 E39 M5
2002 E46 M3
2021 X5 40i -
Damn....going to tell the wife about elitedaily.com we've been going strong because of it.
-
We now need an elite daily thread. REKIII, get us rolling
-
I will admit, that calculator seems biased towards buying a home. I think it can be a valuable tool, but it's generalized and there are so many other unique factors for every person.
-
Buying a home will, in general, be a better option for most of the population. The numbers don't work, when figured like ILC or I have described, but most people, or the average person, will not invest the difference when renting, therefore ending up with less than if you had bought.
-
Buying a home will, in general, be a better option for most of the population. The numbers don't work, when figured like ILC or I have described, but most people, or the average person, will not invest the difference when renting, therefore ending up with less than if you had bought.
this is so very true. You have to take what I say with a grain of salt because 99% of the population is not willing to sacrifice or do what I do. My friends used to think I was a millionaire because I was quote unquote "in real estate", meanwhile I'm sitting there on my hands and knees scraping up 4 layers of tile on a bathroom floor in a building that I was pretty sure was going to kill my health.
But it doesn't change the fact that I'm being totally honest about everything if the goal for a person reading this is to actually do something more with their lives instead of go to work, come home and do the family thing and watch American Idol or whatever the fuck is on tv these days.
2011 E92 M3 6MT ZCP - ESS 625 supercharged
2007 Z4MR
2003 E39 M5
2002 E46 M3
2021 X5 40i -
I don't have cable. So it's the people's court for me.
Hello! It looks like you're interested in this conversation, but you don't have an account yet.
Getting fed up of having to scroll through the same posts each visit? When you register for an account, you'll always come back to exactly where you were before, and choose to be notified of new replies (either via email, or push notification). You'll also be able to save bookmarks and upvote posts to show your appreciation to other community members.
With your input, this post could be even better 💗
Register Login